
Kitten Insurance: Cost, Coverage & When to Enroll Your Kitten
Kitten insurance can help cover unexpected veterinary expenses if your kitten becomes sick or injured. Coverage commonly costs around $20 to $30 per month, although breed, location, deductible, reimbursement and annual limits can significantly change the price. The best time to consider pet insurance for a kitten is generally while your kitten is young and healthy, before medical conditions or symptoms appear in the veterinary record.
As cat breeders, we discuss insurance with families before their kittens go home because waiting periods, pre-existing conditions and coverage dates can matter just as much as the monthly premium.
Looking for a company? See our Pet Insurance for Cats: Complete Comparison for our provider comparisons, coverage analysis, cost comparisons and Almonte Cat Insurance Scores.
Kitten Insurance at a Glance
| Question | Quick Answer |
|---|---|
| How much does kitten insurance cost? | Often around $20–$30 per month, depending on the kitten and coverage selected |
| When should you enroll? | While your kitten is young and healthy |
| Are accidents covered? | Usually, with accident or accident and illness coverage |
| Are illnesses covered? | Usually, with accident and illness coverage |
| Is emergency surgery covered? | Generally, when the condition and expenses are eligible under the policy |
| Are hereditary conditions covered? | Depends on the policy |
| Are congenital conditions covered? | Depends on the policy |
| Are vaccinations covered? | Usually through optional wellness or preventive coverage, not standard accident and illness insurance |
| Is spaying or neutering covered? | Usually not under accident and illness insurance, although some wellness plans provide benefits |
| Are pre-existing conditions covered? | Generally excluded, although definitions and rules vary by insurer |
| Is there a waiting period? | Usually. Coverage does not necessarily begin immediately after enrollment |
How Much Is Kitten Insurance?
As a general benchmark, MoneyGeek currently reports an average cost of approximately $23 per month for kittens under one year old using a standardized policy with a $5,000 annual limit, $500 deductible and 80% reimbursement.
That number should be treated as a reference point rather than the price you should expect to pay. Kitten insurance cost can change considerably based on the kitten’s breed, ZIP code and the amount of coverage selected. A plan with a $1,000 deductible and lower reimbursement cannot be directly compared with a plan offering a $250 deductible, 90% reimbursement and unlimited annual coverage.
For that reason, later in this guide we compare kitten insurance using equivalent coverage settings whenever possible. This makes it easier to see whether a lower premium actually represents better value or simply less coverage.
What Is Kitten Insurance?
Kitten insurance is pet health insurance purchased for a young cat. Depending on the plan, it can help reimburse eligible veterinary expenses when a kitten is injured or becomes sick.
There are three main types of coverage to understand:
| Coverage Type | What It Does |
|---|---|
| Accident-Only | Covers eligible unexpected injuries, such as wounds, broken bones or accidental ingestion |
| Accident + Illness | Covers eligible accidents plus illnesses, diagnostics, hospitalization, surgery and other covered treatment |
| Wellness / Preventive Care | Helps with predictable routine expenses such as exams, vaccinations and other preventive care, depending on the plan |
Accident and illness insurance is designed primarily for unexpected veterinary expenses. In contrast, wellness coverage helps pay for routine care you already expect your kitten to need.
Therefore, a plan advertised as including “kitten wellness” should not automatically be considered equivalent to comprehensive accident and illness insurance.
When Should You Get Pet Insurance for a Kitten?
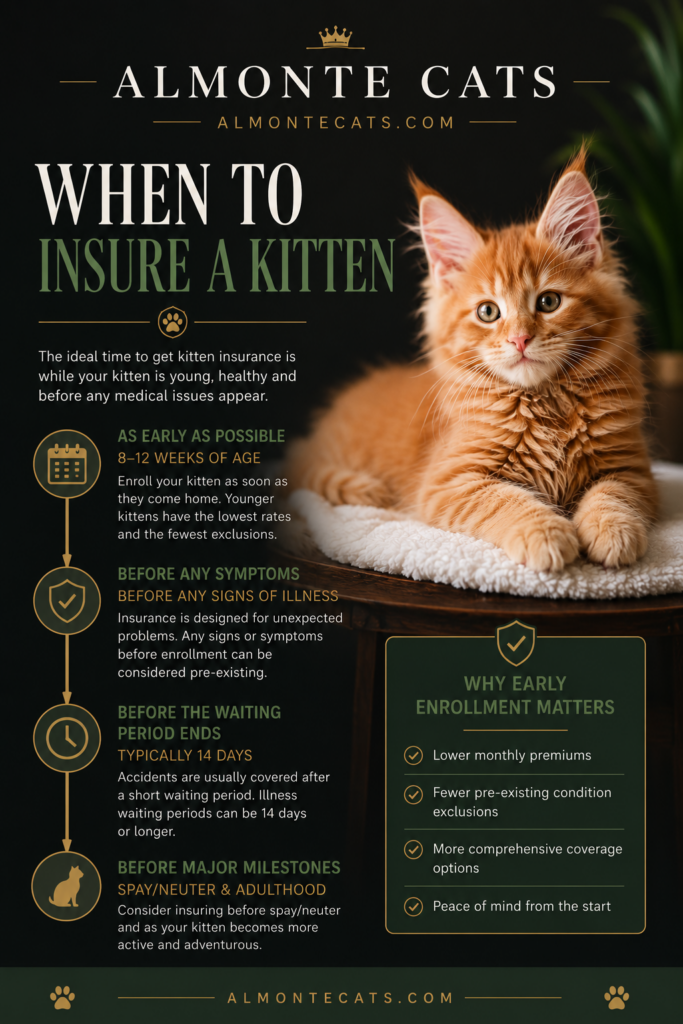
The best time to consider pet insurance for a kitten is generally while your kitten is young and healthy, before unexpected symptoms, injuries or illnesses appear in the medical record.
However, purchasing a policy does not always mean coverage begins immediately. Most pet insurance policies have an effective date followed by waiting periods for certain types of coverage.
A typical enrollment looks like this:
Enrollment → Waiting Period → Coverage Begins → Future Eligible Conditions
The exact waiting period depends on the insurance company, policy and state. Therefore, it is important to know not only when you purchased insurance, but also when your kitten’s accident and illness coverage actually becomes effective.
Why Getting Kitten Insurance Early Matters
Pet insurance generally does not cover pre-existing conditions. Additionally, a condition does not always need a formal diagnosis to be considered pre-existing.
Symptoms documented before coverage begins or during an applicable waiting period can potentially affect coverage for a condition diagnosed later.
For example:
Healthy kitten → Insurance activated → Waiting period completed → New illness develops
is very different from:
Symptoms develop → Insurance purchased → Diagnosis occurs later
In the second situation, the insurer may review the earlier symptoms when determining whether the condition was pre-existing.
For this reason, we encourage families to understand their insurance options before they actually need to make a claim.
How Young Can a Kitten Get Pet Insurance?
Kittens can qualify for pet insurance surprisingly young. However, minimum enrollment ages and waiting periods vary between companies.
| Provider | Minimum Enrollment Age | Accident Waiting Period | Illness Waiting Period |
|---|---|---|---|
| Trupanion | Varies by enrollment method | 5 days* | 30 days* |
| Embrace | 6 weeks | Effective-date coverage* | 14 days* |
| Pets Best | 7 weeks | Varies by state* | Varies by state* |
| Pumpkin | 8 weeks | Up to 14 days* | Up to 14 days* |
| Fetch | 6 weeks | Varies by location* | Varies by location* |
*These are general enrollment terms and can change or vary by state, policy and enrollment method. Always check the current policy documents before purchasing coverage.
A Note for Almonte Cats Families
Almonte Cats kittens have a different Trupanion enrollment option than someone purchasing a standard policy independently.
As a participating breeder, we send our kittens home with access to Trupanion’s Go Home Day Offer through its breeder program.
When an eligible family activates the offer within Trupanion’s required activation window, the usual waiting-period gap is waived and coverage can begin immediately upon activation. The offer provides 30 days of Trupanion coverage for eligible new and unexpected illnesses and injuries, subject to Trupanion’s terms and exclusions.
For our kitten families, timing matters. The Go Home Day Offer must be activated within the specified window surrounding your kitten’s go-home date. We recommend activating it promptly rather than putting it aside with the rest of your kitten paperwork.
The new owner must complete the activation. Almonte Cats cannot activate the insurance on your behalf.
After the initial offer period, families can decide whether they want to continue with Trupanion coverage.
This is one reason we send our kittens home with the Trupanion offer. It helps eliminate the standard waiting-period gap during a time when a kitten is transitioning into a new home.
When Does Kitten Insurance Coverage Begin?
For a kitten enrolled through a standard pet insurance policy, the timeline generally looks like this:
Enroll Kitten → Policy Begins → Waiting Period → Accident/Illness Coverage Becomes Effective
For an eligible Almonte Cats kitten using the properly activated Trupanion Go Home Day Offer, the timeline is different:
Kitten Goes Home → Activate Go Home Day Offer → Waiting Period Waived → Coverage Begins → First Veterinary Visit → Decide Whether to Continue Coverage
Regardless of the enrollment method, coverage remains subject to the insurer’s policy terms. Activating insurance does not make an illness, injury or symptom that already qualifies as pre-existing suddenly eligible for coverage.
Should You Get Kitten Insurance Before the First Vet Visit?
There can be an advantage to arranging pet insurance early, but you should never postpone necessary veterinary care simply to establish insurance coverage first.
Veterinary care and insurance eligibility serve two different purposes.
Your veterinarian examines, diagnoses and treats your kitten. Your insurance company determines whether those veterinary expenses qualify for reimbursement under your policy.
When evaluating a claim, an insurer may review information in your kitten’s medical record, including:
Physical examinations | Symptoms | Diagnoses | Diagnostic testing | Previous treatment | Medications
Therefore, the date of the final diagnosis is not necessarily the only date that matters.
For example, suppose a veterinary record documents recurring vomiting before insurance coverage becomes effective. If the kitten is later diagnosed with a condition associated with that symptom, the insurer may review those earlier records when determining whether the condition qualifies as pre-existing.
For families bringing home a kitten, the goal should be simple:
Establish appropriate veterinary care promptly and understand exactly when your kitten’s insurance coverage becomes effective.
For Almonte Cats families, that also means activating the Trupanion Go Home Day Offer within the required window so the special breeder benefit is not lost.

How Much Does Kitten Insurance Cost?
Kitten insurance costs about $23 per month on average, although there is no single price that applies to every kitten. MoneyGeek’s current national analysis found an average of approximately $23 per month, or $272 per year, for kittens under one year old using a $5,000 annual limit, $500 deductible and 80% reimbursement rate.
That average is useful as a benchmark, but it can also be misleading if the coverage isn’t identical. A $15 monthly policy with a $1,000 deductible and lower reimbursement is not directly comparable to a $40 policy with a $250 deductible, 90% reimbursement and a much higher annual limit.
For this reason, we compare kitten insurance cost using the same kitten profile and equivalent coverage whenever possible.
Kitten Insurance Cost Comparison
For our comparison, use the same kitten age, breed, sex and Pennsylvania ZIP code. The target coverage is a $500 deductible, 80% reimbursement and $5,000 annual limit, or the closest option offered by the insurer.
| Provider | Monthly | Annual | Deductible | Reimbursement | Annual Limit |
|---|---|---|---|---|---|
| Trupanion | $42* | $504* | $500 | 90% | Unlimited |
| Embrace | $27* | $324* | $500 | 80% | $5,000 |
| Pets Best | $24* | $288* | $500 | 80% | $5,000 |
| Pumpkin | $28* | $336* | $500 | 80% | $5,000 |
| Fetch | $29* | $348* | $500 | 80% | $5,000 |
*Illustrative standardized quotes for building our comparison. Replace these premiums with the final quotes collected for the same kitten profile before publication.
Trupanion cannot be compared perfectly with the other policies in this table because its standard coverage structure differs. That is exactly why comparing premiums without looking at the policy can be misleading.
What We Found
In our example, monthly kitten insurance premiums ranged from approximately $24 to $42 per month. However, the least expensive policy was not automatically the policy providing the most coverage.
For comparison, MoneyGeek’s much larger national dataset of more than 67,000 kitten profiles found an average of $23 per month using a Ragdoll kitten under one year old with a $500 deductible, 80% reimbursement and $5,000 annual limit.
The important question isn’t simply “How much is kitten insurance?”
It is:
How much does comparable kitten insurance cost for my kitten?
That distinction makes premiums much easier to evaluate.
What Changes the Cost of Kitten Insurance?
Several factors can change a kitten insurance quote, even when two kittens are the same age.
| Factor | How It Can Affect Cost |
|---|---|
| Breed | Insurers may price breeds differently based on expected claims and health risks |
| Location | Veterinary costs and insurance pricing vary geographically |
| Deductible | A higher deductible will often reduce the monthly premium |
| Reimbursement | Higher reimbursement can increase the premium |
| Annual Limit | Higher or unlimited coverage can cost more |
| Coverage | Broader coverage and additional benefits can increase cost |
MoneyGeek’s current data shows particularly large differences when coverage settings change. In its analysis, kitten premiums varied from about $15 to $43 per month depending on coverage selections, while breed and geographic location also affected premiums.
Does Breed Affect Kitten Insurance Cost?
Yes. Insurers can quote different premiums for different breeds even when the kittens are otherwise identical.
MoneyGeek’s current analysis found Domestic Shorthair kittens among the lower-cost breeds at approximately $20 per month, while several purebred cats, including Maine Coons and British Shorthairs, fell into higher-cost groups.
For families with a purebred kitten, however, price is only part of the comparison. We also look closely at hereditary and congenital condition coverage, which becomes especially important when evaluating insurance for breeds with known inherited health concerns.
What Does Kitten Insurance Cover?
A comprehensive accident and illness policy is designed primarily for unexpected veterinary expenses. Depending on the policy, this can include injuries, illnesses, diagnostics, surgery, hospitalization and prescription medications.
Routine kitten care works differently. Vaccinations, routine examinations, deworming and other predictable expenses generally fall under wellness or preventive-care coverage rather than standard accident and illness insurance.
| Expense | Accident + Illness | Wellness / Preventive Care |
|---|---|---|
| Accidents | ✓ | |
| Illness | ✓ | |
| Emergency care | ✓ | |
| Diagnostics | ✓ | |
| Surgery | ✓ | |
| Hospitalization | ✓ | |
| Prescription medications | ✓ | |
| Hereditary conditions | Policy dependent | |
| Congenital conditions | Policy dependent | |
| Dental illness | Policy dependent | |
| Routine exams | Usually not* | ✓ |
| Vaccinations | ✓ | |
| Routine deworming | ✓ | |
| Microchipping | ✓ | |
| Spay/neuter | Plan dependent |
*Some accident and illness policies or optional add-ons may cover eligible veterinary exam fees. Always check the individual policy.
Accident and Illness Coverage
This is the part of kitten insurance designed to protect against potentially expensive, unexpected veterinary treatment.
For example, an eligible policy could potentially help with expenses associated with:
A swallowed foreign object | Broken bone | Unexpected illness | Emergency hospitalization | Diagnostic imaging | Surgery | Prescription treatment
Coverage remains subject to the deductible, reimbursement rate, annual limit, exclusions and other policy terms.
Wellness Coverage
Wellness coverage serves a different purpose.
Instead of protecting primarily against an unexpected $3,000 emergency, a wellness plan helps offset predictable expenses that commonly occur during a kitten’s first year.
Depending on the plan, benefits may be available for:
Routine examinations | Vaccinations | Deworming | Microchipping | Preventive testing | Spaying or neutering
That distinction is important because a kitten can have excellent accident and illness insurance and still receive no reimbursement for routine vaccinations.
PetMD likewise separates accident, accident-and-illness and wellness coverage when explaining kitten insurance, including routine services such as vaccinations, deworming and microchipping under preventive care rather than treating them as standard illness benefits.
Which Coverage Matters Most for a Kitten?
For routine first-year expenses, wellness coverage can make costs more predictable.
For the expenses that are difficult to predict, accident and illness coverage provides the more important financial protection.
A vaccination series can generally be planned for. A kitten swallowing a foreign object and unexpectedly requiring several thousand dollars in emergency surgery cannot.
That is why we evaluate these two types of coverage separately rather than treating a wellness plan and pet insurance for kittens as the same product.

What Kitten Insurance Does Not Cover
Even comprehensive kitten insurance has exclusions. Understanding what a policy does not cover is just as important as knowing what it does.
Common exclusions include:
- Pre-existing conditions: Conditions or symptoms that existed before coverage began may be excluded.
- Expenses during waiting periods: An illness or injury that develops during an applicable waiting period may not be covered.
- Routine care: Vaccinations, routine exams, deworming and other preventive care generally require separate wellness coverage.
- Elective procedures: Procedures that are not medically necessary are commonly excluded.
- Breeding and pregnancy: Costs associated with breeding, pregnancy or giving birth are excluded by many policies.
- Policy-specific exclusions: Every insurer has its own exclusions, limitations and definitions, so the actual policy should always be reviewed.
Kitten Insurance and Pre-Existing Conditions
Pre-existing conditions are particularly important when buying pet insurance for a kitten because insurance is designed to cover eligible conditions that arise after coverage begins, not medical problems that already existed.
However, the date of diagnosis is not necessarily the date an insurance company uses to determine when a condition began.
Before vs After Kitten Insurance Coverage
| Event | Potential Coverage |
|---|---|
| Symptom before enrollment | May be considered pre-existing |
| Diagnosis before enrollment | Generally considered pre-existing |
| Symptom during waiting period | May be excluded |
| New eligible illness after waiting period | Potentially covered |
| New eligible accident after waiting period | Potentially covered |
Coverage ultimately depends on the insurer’s definition of a pre-existing condition, the kitten’s medical records and the terms of the individual policy.
Does It Have to Be Diagnosed to Be Pre-Existing?
No. A condition does not necessarily need a formal diagnosis to be considered pre-existing.
An insurance company may consider symptoms that occurred or were documented before coverage began, even when the veterinarian did not know the underlying cause at the time.
For example, imagine that a kitten develops recurring digestive symptoms before insurance coverage begins. Several months later, testing identifies an underlying condition responsible for those symptoms. The insurer may review the earlier veterinary records when determining whether the later diagnosis is related to a pre-existing condition.
This is why the medical timeline matters:
Symptoms Begin → Insurance Enrollment → Coverage Begins → Diagnosis
is very different from:
Insurance Enrollment → Waiting Period Ends → New Symptoms Begin → Diagnosis
The second timeline does not automatically guarantee coverage, but it establishes that the symptoms first appeared after coverage became effective.
What About Curable Pre-Existing Conditions?
This is another reason to read individual policies carefully. Some insurers distinguish between curable and incurable pre-existing conditions and may reconsider certain curable conditions after a required symptom-free period.
Others may handle them differently.
Therefore, when comparing kitten insurance, look beyond a simple statement that says “pre-existing conditions are not covered.” Check how the insurer defines:
Pre-existing condition | Signs and symptoms | Curable conditions | Bilateral conditions | Waiting periods | Medical-record review
Those definitions can have a much greater effect on future coverage than a small difference in the monthly premium.

Kitten Insurance Waiting Periods Explained
A kitten insurance waiting period is the time between enrolling in a policy and when certain coverage becomes available.
A standard policy may look like this:
Buy Policy → Waiting Period → Coverage Begins
Accident and illness coverage do not always begin on the same day. For example, an insurer may have a shorter waiting period for accidents and a longer waiting period for illnesses. Other companies use the same waiting period for both.
If a kitten develops symptoms or is injured during an applicable waiting period, expenses associated with that condition may not be covered even if treatment continues after the waiting period ends.
This is one reason when you enroll your kitten matters. Buying insurance after a medical problem appears does not make that condition eligible simply because the policy becomes active later.
Almonte Cats families should also remember that our Trupanion Go Home Day Offer works differently from standard enrollment. When properly activated within the required timeframe, the applicable standard waiting periods are waived.
Does Kitten Insurance Cover Hereditary Conditions?
Many accident and illness policies can cover eligible hereditary and congenital conditions, but coverage varies significantly between policies.
Three terms are particularly important:
| Term | What It Means |
|---|---|
| Hereditary condition | A condition associated with inherited genetic factors |
| Congenital condition | A condition present at birth, although it may not become apparent until later |
| Pre-existing condition | A condition, illness, injury or associated signs that existed before applicable coverage began, according to the insurer’s definition |
These terms are not interchangeable.
A hereditary condition is not automatically a pre-existing condition simply because a breed has a known predisposition to it. Likewise, purchasing insurance for a purebred kitten does not mean every breed-associated condition will automatically be covered.
The important questions are whether the policy covers hereditary and congenital conditions and whether the individual kitten had signs, symptoms or a diagnosis before coverage became effective.
Pet Insurance for Purebred Kittens
Purebred kittens can benefit from the same accident and illness coverage as other cats, but we pay particular attention to the hereditary and congenital condition language when comparing policies.
Being a particular breed does not mean a kitten will develop a breed-associated health condition. However, different breeds can have documented predispositions to certain diseases, which makes the wording of the insurance policy worth reviewing before enrollment.
Maine Coon Kittens
Maine Coons have documented breed predispositions to certain inherited conditions, including hypertrophic cardiomyopathy (HCM). Families considering insurance should check how the policy handles hereditary conditions, congenital conditions, cardiac disease and pre-existing conditions.
Related: Maine Coon Health →
Ragdoll Kittens
Ragdolls also have recognized hereditary health considerations, including HCM. For a Ragdoll kitten, we would look beyond the monthly premium and compare the policy’s hereditary and congenital coverage, exclusions and medical-record requirements.
Related: Ragdoll Health →
British Shorthair Kittens
British Shorthairs have their own breed-specific health considerations. As with any purebred kitten, insurance should be evaluated based on the individual policy rather than assuming that a condition is covered simply because the company advertises hereditary coverage.
Related: British Shorthair Health →
What We Look for in Purebred Kitten Insurance
For a purebred kitten, we pay particular attention to:
Hereditary coverage | Congenital coverage | Chronic conditions | Bilateral conditions | Annual limits | Pre-existing condition definitions | Medical-record review
A policy that costs a few dollars less each month may not be the better value if it provides substantially different coverage for conditions that matter to your cat.
For purebred kittens, we pay particular attention to hereditary and congenital coverage rather than choosing insurance solely by monthly premium.
Does Kitten Insurance Cover Vaccinations?
Standard accident and illness kitten insurance generally does not cover routine vaccinations.
Vaccines are considered predictable preventive care rather than treatment for an unexpected accident or illness. However, some insurers offer optional wellness or preventive-care plans that provide an allowance toward routine kitten vaccinations.
Depending on the plan, wellness benefits may help with vaccines such as FVRCP and rabies, along with other routine first-year care.
Before adding wellness coverage, check the annual vaccination benefit and compare it with what the add-on costs. A plan that includes vaccines is not necessarily paying the entire vaccination bill.
Related: Kitten Vaccination Schedule →

Does Kitten Insurance Cover Spaying or Neutering?
Standard accident and illness insurance usually does not cover routine spaying or neutering.
Spay and neuter procedures are generally considered planned preventive care rather than unexpected medical treatment.
However, some wellness and preventive-care plans provide a specific benefit or allowance toward spaying or neutering. The amount varies considerably between plans, so look at the actual reimbursement available rather than assuming the procedure will be covered in full.
This distinction is important when comparing kitten plans. An insurer may advertise coverage for spaying or neutering, but that benefit may come from a separately priced wellness package rather than the underlying insurance policy.
Does Kitten Insurance Cover Deworming?
Routine kitten deworming generally is not covered by standard accident and illness insurance.
Preventive deworming is typically considered routine care. Therefore, reimbursement usually requires a wellness or preventive-care plan that specifically includes it.
Treatment for an illness caused by parasites can be different. Depending on the policy, circumstances, medical history and exclusions, treatment for an eligible illness may fall under accident and illness coverage.
Kitten Insurance vs Wellness Plans
Kitten insurance and kitten wellness plans are not the same thing.
The easiest way to understand the difference is to consider whether the expense is unexpected or predictable.
| Expense | Kitten Insurance | Wellness Plan |
|---|---|---|
| Accidents | ✓ | |
| Illness | ✓ | |
| Emergency surgery | ✓ | |
| Hospitalization | ✓ | |
| Vaccinations | ✓ | |
| Routine exams | ✓ | |
| Routine deworming | ✓ | |
| Spay/neuter | Plan dependent | |
| Preventive care | ✓ |
Coverage varies by insurer and policy.
Insurance protects primarily against unexpected eligible medical expenses. Wellness plans help budget for predictable preventive care.
For example, you know when bringing home a kitten that vaccinations and routine veterinary visits are coming. You cannot predict whether that same kitten will swallow something six months later and require emergency surgery.
That is the fundamental difference between the two products.
Is a Kitten Wellness Plan Worth It?
A kitten wellness plan can be worth it when the benefits you expect to use justify the additional cost, but it should not automatically be added simply because you have a young kitten.
Start with two numbers:
Annual cost of wellness coverage
versus
Value of the benefits you realistically expect to use
For example:
| Wellness Plan | Example Amount |
|---|---|
| Additional monthly cost | $25 |
| Annual wellness premium | $300 |
| Maximum available routine-care benefits | $450 |
| Benefits you realistically expect to use | $320 |
In this example, the plan technically offers $450 in benefits. However, if you expect to use only $320 of those benefits, the practical difference between paying $300 for the plan and receiving $320 in benefits is just $20.
This is why the advertised maximum benefit can be misleading.
Look individually at allowances for:
Exams | Vaccinations | Deworming | Testing | Microchipping | Spay/neuter
Then calculate whether you would actually purchase those services without the plan.
Wellness coverage is primarily a budgeting tool for predictable veterinary expenses. It should be evaluated separately from the financial protection provided by accident and illness insurance.
What Deductible Should You Choose for a Kitten?
The deductible is the amount specified by the policy that applies before reimbursement is calculated. Generally, choosing a higher deductible reduces the monthly premium but increases the amount you may need to pay yourself when a claim occurs.
| Deductible | Monthly Premium | Out-of-Pocket Risk |
|---|---|---|
| $250 | Higher | Lower |
| $500 | Middle | Middle |
| $1,000 | Lower | Higher |
There is no single best deductible for every kitten owner.
A lower deductible may make sense if you are comfortable paying more each month in exchange for potentially lower out-of-pocket costs when eligible claims occur. A higher deductible can reduce the monthly premium but requires being prepared for a larger veterinary expense yourself.
Also check whether the insurer uses an annual deductible or a per-condition deductible, because the two structures work differently.
70% vs 80% vs 90% Pet Insurance Reimbursement
The reimbursement percentage determines how much of an eligible covered expense the insurer reimburses after the applicable deductible and according to the policy’s calculation method.
Consider a $2,000 covered kitten emergency with a $500 deductible.
| Reimbursement | Insurance Pays* | Owner Pays* |
|---|---|---|
| 70% | $1,050 | $950 |
| 80% | $1,200 | $800 |
| 90% | $1,350 | $650 |
Example assumes the $500 deductible is applied first, all $2,000 of expenses are eligible, and reimbursement is calculated on the remaining $1,500. Actual claim calculations vary by policy.
The difference becomes more significant as veterinary bills increase. However, higher reimbursement percentages also tend to come with higher monthly premiums.
That is why 90% reimbursement is not automatically the best kitten insurance option. The deductible, annual limit, monthly premium and covered expenses all need to be considered together.
Is Pet Insurance Worth It for a Kitten?
Pet insurance can be worth it for a kitten when the cost of an unexpected veterinary emergency would be difficult to absorb without insurance. However, whether it makes financial sense depends on the policy, premium, deductible, coverage and your ability to pay veterinary expenses yourself.
The easiest way to evaluate it is to look at different first-year scenarios.
| First-Year Scenario | Potential Insurance Value |
|---|---|
| Healthy kitten | May receive little or no accident and illness reimbursement |
| Minor accident | Benefit may be limited depending on the deductible |
| $2,000 emergency | Insurance may substantially reduce eligible out-of-pocket costs |
| Major surgery | Higher reimbursement and annual limits become increasingly important |
| Chronic condition diagnosed after coverage begins | Eligible long-term treatment can make continued coverage particularly valuable |
A healthy kitten may go an entire year without generating a reimbursable claim. In that situation, you could pay more in premiums than you receive back.
The calculation changes quickly when something unexpected happens. Diagnostic imaging, emergency hospitalization or surgery can produce a veterinary bill of several thousand dollars in a very short period of time.
There is also a longer-term consideration. If an eligible chronic condition develops after coverage is established, maintaining continuous coverage may help with qualifying treatment expenses in subsequent years, subject to the policy terms.
Pet Insurance vs an Emergency Fund
The alternative to purchasing insurance is often self-funding veterinary expenses.
With insurance, you pay a predictable premium in exchange for transferring some of the financial risk of eligible veterinary expenses to an insurer.
With an emergency fund, you keep that money yourself but remain responsible for the entire veterinary bill.
| Pet Insurance | Emergency Fund | |
|---|---|---|
| Monthly expense | Premium | Amount you choose to save |
| Money available immediately | Depends on coverage and claim | Limited to amount already saved |
| Large unexpected bill | May reimburse eligible expenses | You pay entire bill |
| Deductible | Usually | No |
| Coverage exclusions | Yes | No |
| Pre-existing condition restrictions | Yes | No |
| Money remains yours if unused | No | Yes |
Neither approach is automatically better for every family.
The more useful question is: If your kitten needed several thousand dollars of unexpected veterinary care tomorrow, how would you pay for it?
Your answer can help determine whether insurance, self-funding or a combination of both makes the most sense.

What I Tell Families Before Their Kitten Goes Home
We discuss insurance with our families before their kittens leave because the time to understand a policy is before you need to file a claim.
Understand Your Insurance Before Pickup
Know which plan you have, what it covers and whether you need to take any steps to activate coverage.
Know When Coverage Begins
Purchasing or activating insurance does not always mean every type of coverage begins immediately. Check the effective date and any applicable waiting periods.
Almonte Cats families using the Trupanion Go Home Day Offer should activate the offer within the required timeframe to receive the breeder-program benefits.
Keep Your Kitten’s Veterinary Records
Save your kitten’s breeder health records, veterinary examinations, test results, vaccination records and future medical records. Your insurance company may request this history when reviewing a claim.
Understand Pre-Existing Conditions
Read the insurer’s definition of a pre-existing condition. A condition does not necessarily need a formal diagnosis to be considered pre-existing. Symptoms documented before coverage begins can matter.
Know Your Deductible
Understand how much you are responsible for before reimbursement applies. A $500 deductible and a $1,000 deductible can produce very different out-of-pocket costs during an emergency.
Check Your Reimbursement Percentage
A covered claim does not usually mean the insurance company pays the entire veterinary bill. Know whether your plan reimburses 70%, 80%, 90% or another percentage of eligible expenses.
Find Out Who Pays the Veterinarian
Many pet insurance companies use a reimbursement model. You pay the veterinary hospital first and submit a claim afterward.
Some insurers offer direct vet payment in certain circumstances. If paying a large veterinary bill upfront would be difficult, this is worth understanding before choosing a policy.
Don’t Confuse Wellness Coverage With Insurance
Routine vaccinations, deworming, wellness exams and other predictable kitten expenses may require separate preventive or wellness coverage.
Accident and illness insurance is primarily designed for unexpected eligible veterinary expenses.
Understand What “Covered” Actually Means
This is probably the most important thing I tell families: covered does not mean the insurance company will pay every dollar on the veterinary bill.
Your deductible, reimbursement percentage, annual limit, exclusions and individual policy terms can all affect what you ultimately pay.
For our kitten families, I would much rather have these questions answered before go-home day than have someone trying to understand their insurance policy while sitting in an emergency veterinary hospital.
How to Choose Pet Insurance for a Kitten
There isn’t one policy structure that makes sense for every kitten. Start by deciding what matters most to you, then compare policies on those specific features.
| If Your Priority Is… | Look For… |
|---|---|
| Purebred kitten | Hereditary + congenital condition coverage |
| Major emergencies | High or unlimited annual limit |
| Lower monthly premium | Higher deductible, while considering your ability to pay it |
| Dental illness | Explicit dental illness coverage |
| Routine kitten care | Optional wellness/preventive coverage |
| Less upfront expense | Direct vet payment options |
| Long-term illness | Chronic-condition coverage and renewal terms |
| Multiple kittens | Multi-pet discounts |
Look Beyond the Monthly Premium
A lower premium does not necessarily mean better value.
Before choosing pet insurance for a kitten, compare:
Coverage → Exclusions → Deductible → Reimbursement → Annual Limit → Hereditary Coverage → Dental Coverage → Waiting Periods → Direct Pay
A $20 monthly policy can ultimately provide less financial protection than a $35 policy, or it can be exactly what you need. The policy details determine the difference.
Ready to compare individual insurers? See our complete Pet Insurance for Cats comparison →
Mistakes to Avoid When Buying Kitten Insurance
The biggest mistakes with kitten insurance often happen before a claim is ever filed. A policy can look inexpensive or comprehensive at first glance while working very differently once you read the details.
Choosing Based Only on the Monthly Premium
The cheapest policy is not necessarily the best value. A lower premium may come with a higher deductible, lower reimbursement percentage, smaller annual limit or more restrictive coverage.
Compare equivalent coverage before comparing price.
Assuming Insurance and Wellness Coverage Are the Same
Accident and illness insurance primarily covers eligible unexpected medical expenses. Wellness plans are designed for predictable expenses such as vaccinations, routine exams and deworming.
A plan advertising kitten preventive benefits may not provide the accident and illness protection you expect.
Ignoring Waiting Periods
Coverage may not begin immediately after enrollment. Accident and illness waiting periods can also be different.
If symptoms or an injury occur during an applicable waiting period, related expenses may not be eligible for coverage.
Not Reading the Pre-Existing Condition Definition
Don’t assume a condition must be formally diagnosed before it can be considered pre-existing.
Insurers may review previous symptoms, veterinary notes, diagnostic results and treatment history when evaluating a claim. Read the insurer’s actual definition before enrolling.
Assuming Hereditary Conditions Are Automatically Covered
A company mentioning hereditary conditions does not mean every inherited condition will automatically qualify for reimbursement.
Check hereditary coverage, congenital coverage, exclusions, waiting periods and pre-existing-condition rules separately.
Ignoring the Annual Limit
A policy can look excellent until a major veterinary bill exceeds its annual benefit.
For example, the difference between a $5,000 annual limit and unlimited annual coverage may matter very little during a healthy year but become significant during hospitalization, surgery or treatment for a serious illness.
Comparing Policies With Different Coverage
This is one of the easiest ways to make a poor comparison.
A policy offering:
$1,000 deductible + 70% reimbursement + $5,000 annual limit
should not be directly compared on price with:
$250 deductible + 90% reimbursement + unlimited coverage
Whenever possible, keep the deductible, reimbursement percentage and annual limit the same when requesting quotes.
Waiting Until Your Kitten Has a Health Problem
One of the worst times to start researching insurance is after a kitten develops symptoms or receives a diagnosis.
Buying a policy afterward does not make an existing medical problem eligible for coverage. Previous symptoms may also affect how a later diagnosis is classified.
For this reason, we encourage families to understand their kitten insurance options while their kitten is young and healthy, rather than waiting until they need veterinary care to start reading policy documents.
Frequently Asked Questions About Kitten Insurance
How much is kitten insurance?
Kitten insurance often costs around $20 to $30 per month, although premiums vary considerably. Your kitten’s breed, age, location and selected coverage can all affect the price. Deductible, reimbursement percentage and annual limit also matter, so compare policies using similar coverage rather than simply choosing the lowest monthly premium.
Is pet insurance worth it for a kitten?
Pet insurance can be worth it if an unexpected veterinary bill would be difficult to pay yourself. A healthy kitten may have few or no reimbursable expenses during the first year. However, an accident, emergency surgery or eligible illness can quickly result in thousands of dollars in veterinary expenses.
When should I get pet insurance for my kitten?
Generally, the best time to consider pet insurance for a kitten is while your kitten is young and healthy. Most policies exclude pre-existing conditions, and waiting periods may apply before coverage begins. Therefore, it is useful to understand your insurance options before your kitten develops symptoms or needs unexpected veterinary treatment.
What is the best age to get pet insurance for a kitten?
There is no single perfect age, but enrolling while a kitten is young and healthy can reduce the likelihood that medical conditions exist before coverage begins. Some insurers accept kittens as young as six to eight weeks old. Always check the company’s minimum enrollment age and applicable waiting periods.
How young can a kitten get pet insurance?
Some pet insurance companies allow enrollment beginning at approximately six to eight weeks of age. Minimum ages vary by insurer. Additionally, enrollment does not necessarily mean all coverage begins immediately because accident and illness waiting periods may apply.
Should I get pet insurance before my kitten’s first vet visit?
Arranging insurance early can be beneficial, but necessary veterinary care should never be delayed for insurance purposes. Insurers may review previous symptoms, examinations and medical records when evaluating future claims. Ideally, understand both your kitten’s veterinary-care schedule and when insurance coverage becomes effective before bringing your kitten home.
What does kitten insurance cover?
Accident and illness kitten insurance can cover eligible expenses for accidents, illnesses, diagnostics, hospitalization, surgery and prescription medications. Some policies also cover eligible hereditary, congenital and dental conditions. Routine vaccinations, wellness exams and other preventive expenses generally require separate wellness coverage.
Does kitten insurance cover vaccinations?
Standard accident and illness insurance generally does not cover routine kitten vaccinations. However, some insurers offer optional wellness or preventive-care plans that provide vaccination benefits. Check both the additional cost of the wellness plan and the amount it actually reimburses for vaccines.
Does kitten insurance cover spaying or neutering?
Standard accident and illness insurance generally does not cover routine spaying or neutering. However, some optional wellness plans provide an allowance toward the procedure. The amount varies by plan and may cover only part of the total veterinary cost.
Does kitten insurance cover deworming?
Routine preventive deworming generally falls under wellness or preventive care, rather than accident and illness insurance. Some wellness plans provide a deworming benefit. Treatment for an eligible illness involving parasites may be handled differently depending on the policy and circumstances.
Does kitten insurance cover dental care?
Some kitten insurance policies cover eligible dental accidents and dental illnesses, while routine dental care may be excluded or require wellness coverage. Dental benefits vary significantly between insurers, so check dental illness, periodontal disease, extractions and preventive dental care separately.
Does kitten insurance cover hereditary conditions?
Many accident and illness policies can cover eligible hereditary conditions, but this varies by insurer. For purebred kittens in particular, review hereditary coverage, exclusions and pre-existing-condition definitions rather than assuming every breed-associated condition is automatically covered.
Does kitten insurance cover congenital conditions?
Some policies cover eligible congenital conditions, which are conditions present at birth that may not become apparent until later. However, coverage depends on the individual policy and the kitten’s medical history. Congenital, hereditary and pre-existing conditions are separate terms and should not be treated as interchangeable.
Does kitten insurance cover pre-existing conditions?
Most traditional pet insurance policies generally exclude pre-existing conditions. Importantly, a condition may not need a formal diagnosis to qualify as pre-existing. Symptoms documented before coverage begins or during an applicable waiting period can potentially affect a future claim.
Is pet insurance cheaper for kittens?
Pet insurance is often less expensive for kittens than for older cats. However, age is only one pricing factor. Breed, location, deductible, reimbursement percentage, annual limit and selected coverage can all affect the final premium.
Do indoor kittens need pet insurance?
Being indoors does not eliminate the possibility of accidents or illnesses. Indoor kittens can still develop medical conditions, swallow foreign objects, become injured or require emergency treatment. Whether insurance makes financial sense depends on the coverage available and your ability to pay unexpected veterinary expenses yourself.
Can I use any veterinarian with kitten insurance?
Many pet insurance policies allow owners to visit licensed veterinarians rather than requiring a traditional human-health-insurance-style provider network. However, requirements can vary, particularly for direct payment, specialists and treatment outside the United States. Check the individual policy before assuming a veterinarian is eligible.
Can I insure two kittens together?
Yes. You can insure multiple kittens, although each kitten will generally have its own coverage, premium and policy terms. Some companies offer multi-pet discounts. When comparing options, calculate the total household premium and coverage rather than choosing a company solely because it advertises a multi-pet discount.
Our Kitten Insurance Editorial Policy
Almonte Cats uses current policy documents, standardized cost comparisons and authoritative veterinary and insurance sources when researching kitten insurance.
Insurance products and policy terms can change, so we review and update our comparisons regularly. When we publish original quote or cost comparisons, they are clearly identified as Almonte Cats comparison data and use consistent profiles whenever possible.
Almonte Cats may participate in affiliate relationships, advertising, sponsorships and brand partnerships. Payment, sponsorships, advertising and affiliate relationships do not determine our conclusions or recommendations.
For our complete provider-testing methodology, scoring criteria and Almonte Cat Insurance Score, see our Pet Insurance for Cats comparison.
Related Kitten & Insurance Guides
- Pet Insurance for Cats → Full company, cost and policy comparison
- Kitten Vaccination Schedule → Vaccines kittens need and when
- Cat Teeth Cleaning Guide → Dental care, when to brush and more.
- Kitten Growth Chart → Kitten growth and development by age
- Kitten Teething Guide → Kitten teeth, teething and development
- Maine Coon Kitten Health → Health considerations for Maine Coon kittens
- Ragdoll Health → Health considerations for Ragdoll cats
- British Shorthair Health → Health considerations for British Shorthair cats
Sources & References
- National Association of Insurance Commissioners (NAIC)
Pet insurance coverage, exclusions, deductibles, waiting periods and pre-existing conditions.
NAIC Pet Insurance - American Veterinary Medical Association (AVMA)
Veterinary guidance for evaluating pet health insurance.
AVMA Pet Insurance - PetMD
Veterinarian-reviewed guidance on kitten insurance, wellness coverage and routine kitten care.
PetMD Kitten Insurance Guide - Trupanion
Official information about the Breeder Support Program and Go Home Day Offer provided to eligible Almonte Cats families.
Trupanion Go Home Day Offer - Individual Insurer Policy Documents
Current policy documents from Trupanion, Embrace, Pets Best, Pumpkin and Fetch are used for provider-specific coverage, waiting periods and exclusions.
Almonte Cats Data: Original cost comparisons, tables and graphics are based on our standardized comparison process and are separate from external insurance and veterinary sources.



Read the Comments +